Colorado assumable loans: calculate the cash gap first
Flat Rate Realty Team · Published October 19, 2026 · Expanded guide
An attractive advertised mortgage rate does not tell you how much cash you need to buy the home.
The rate is only one part of the decision
An attractive advertised mortgage rate does not tell you how much cash you need to buy the home. Before comparing properties, request the current unpaid principal balance, remaining loan term, payment breakdown, and confirmation of the assumption process. Treat a listing’s assumption claim as a lead to investigate, not an approval. Our Colorado assumable-loan page provides a comparison calculator and property links to start that conversation.
A worked cash-gap example
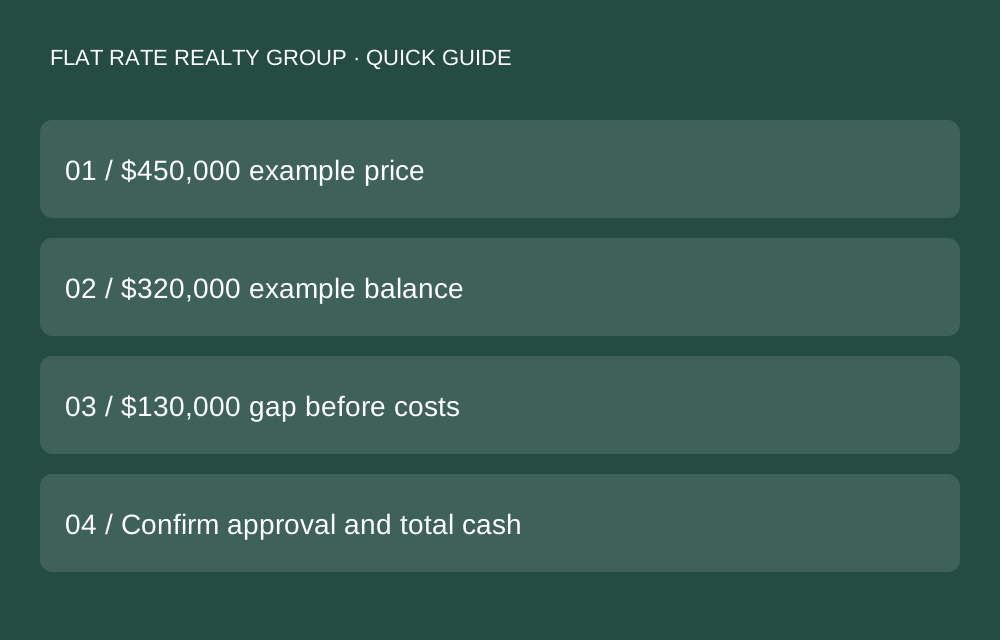
Suppose a home costs $450,000 and its existing mortgage balance is $320,000. The difference is $130,000. That is a starting estimate of the amount outside the assumed mortgage, before closing costs and other adjustments. It is not the same as total cash to close. Do not assume a second loan will cover it: ask the servicer what financing is permitted and compare the combined payment and costs.
Build a comparison sheet
For each option, record the purchase price, loan balance, remaining term, required cash, fees, and estimated monthly housing costs. Keep taxes, insurance, HOA dues, and any additional financing separate from principal and interest. Compare an assumption with a new-loan quote using the same purchase price and realistic closing assumptions. A lower rate can still require more cash than your plan allows.
Questions before an offer
Ask who processes the assumption, which documents are required, whether the buyer qualifies, and how the contract timeline should account for approval. For a VA loan, ask the servicer about release of liability and the seller’s entitlement; these are separate questions to resolve. VA publishes an assumption approval and release-of-liability application. Agree on a backup plan if the assumption cannot proceed.
Separate the payment into useful pieces
Request the principal-and-interest payment separately from the amount collected for property taxes and insurance. A seller’s current total payment is useful background, but it is not your personalized quote. Ask the servicer and your insurance professional which figures may change with the transfer. If the property has an HOA, include its dues and ask about outstanding assessments. Put every recurring expense on one line of your comparison sheet so a low advertised rate does not distract from the overall housing budget.
Compare the same amount of available cash
Imagine you have $150,000 available for the purchase and moving expenses. In the earlier $130,000 gap example, only $20,000 remains before closing charges, repairs, moving costs, and reserves. That does not mean the purchase fits your budget. Ask for an estimate of the complete transaction, then decide how much cash you want left after closing. A new mortgage might require a different cash contribution, but could have different interest costs and payment terms. Compare both paths rather than deciding from the rate alone.
Prepare a property-specific document checklist
For a home you are seriously considering, ask the listing agent how the advertised balance and rate were verified and when those figures were obtained. Request confirmation through the authorized process rather than asking someone to send a seller’s private financial information casually. Track the servicer contact, required application, approval milestones, estimated fees, and outstanding questions. Write down which figures are confirmed and which remain estimates. That simple distinction makes conversations with the lender, agent, and closing professional much clearer.
Questions buyers frequently ask
Does an assumable listing guarantee approval? No: the property advertisement and your eligibility are different matters. Can a buyer use the same timeline as a new mortgage? Ask the servicer for its process and discuss a workable contract with your agent; do not promise a date based on a general article. Does an assumption remove the need for a home inspection? Financing and property condition are separate decisions. What if the balance changes? Update your comparison and cash estimate with current figures before relying on it.
A practical next step for Colorado buyers
Send the Flat Rate Realty Team the property link, asking price, advertised loan information, and your intended moving window. We can help frame the questions to raise with the listing side while you discuss qualification and available funds with the appropriate lender or servicer. If the home is near Fort Carson or you are moving from another state, build temporary housing and travel flexibility into your plan. Keep a second property or financing path in mind until the assumption details are confirmed.
Sources and practical resources
Explore our related services and tools ↗
General planning information. Financing, credits, fees, and services depend on approval and written agreements. Military resources are independent; our brokerage is not affiliated with or endorsed by the military.